Have you got a pension of a previous employer?
|
|
|
|
As we progress through our working lives, maybe moving from employer to employer, we leave behind our workplace pension schemes. These are usually personal pension plans and made “paid up” by the pension company provider. You receive annual statements of your pension plan, which you probably file away, with others, and with the full intention of dealing with them sometime in the future, but usually nearing retirement time.
It is at that time, you come to realise that you have accumulated, some maybe small, a collection of previous employer works pension schemes, and each one now forms part of your overall total pension fund. |
|
|
There are many problems with leaving these small pension pots to near retirement.
Firstly, the pension company may no long exist and probably taken over by another company. The likes of Commercial Union, General Accident, NPI, Countrywide to name a few have been taken over by larger pension companies. Tracking down old pensions can be a nightmare. |
|
|
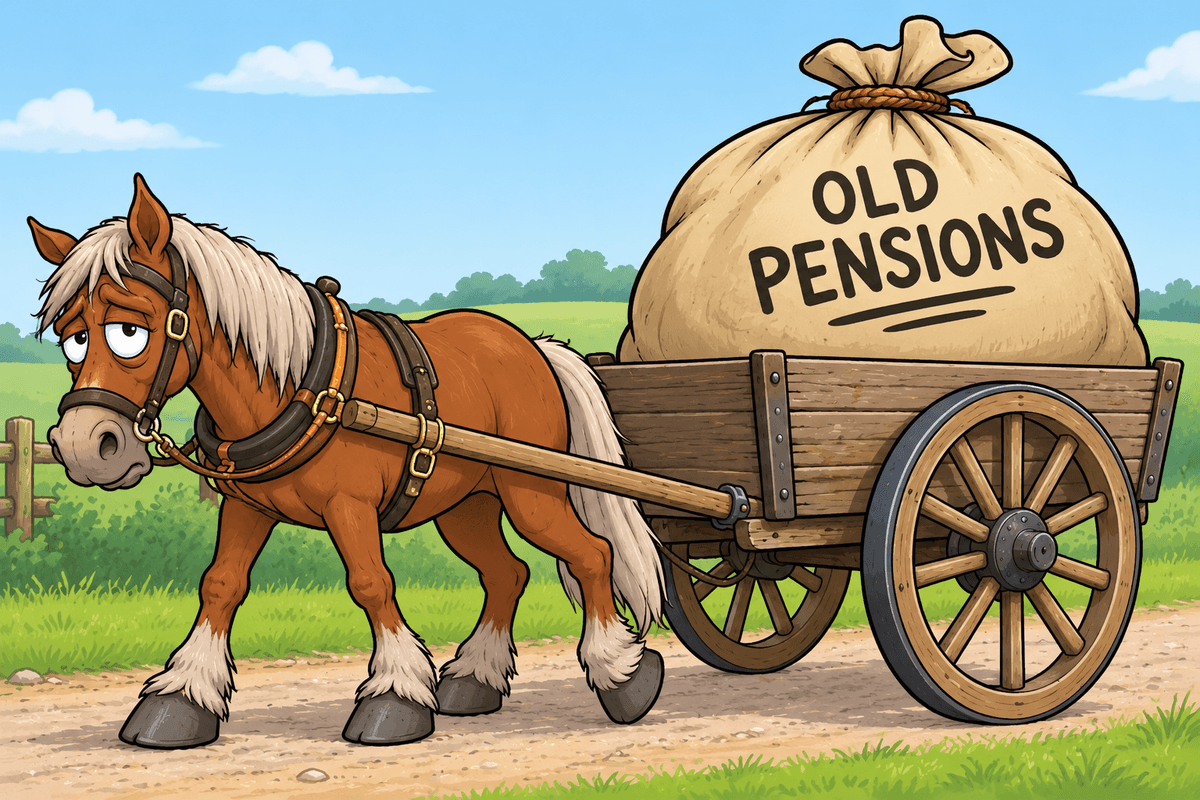
Your pension may be invested in what I call A Carthorse Fund, very large and moves forward very slowly, or even a Dog Fund, named because it has extremely poor performance.
Another problem is that “paid up” pensions usually have very limited choice of funds. |
|
|
However, the main fault with old personal pensions is that they generally only give you two choices on retirement. Use the whole fund to purchase an annuity or commute 25% of the fund for tax free cash and have a reduced annuity. Neither option, equals the flexibility of the New Pensions Freedom of the more modern pension contract. |
|
|
The sensible approach in your pension planning is to collect together all your pension plans of previous employers and have them transferred into a modern Flexible Drawdown Pension Platform. This provides a huge selection of all the top International investment managers so that we can, through research, select the best performing funds to increase your pension on your eventual retirement. This gives you maximum flexibility whilst making additional contributions and total flexibility on the options at retirement.
If you have a “paid-up” pension of a previous employer and would like our advice on what are the best options for your pension planning, then please get in touch. We’ll be glad to help, and hopefully improve your pension income in retirement. |
|
|
Enjoy the Autumn sunshine.
Best regards Ray
|
|
|
|