Taking tax free cash from your Flexible Drawdown pension.
|
|
|
Arranging to take the tax-free element of your pension, either as a cash lump sum or as income, can appear to be somewhat confusing, so here is a simplified explanation to help.
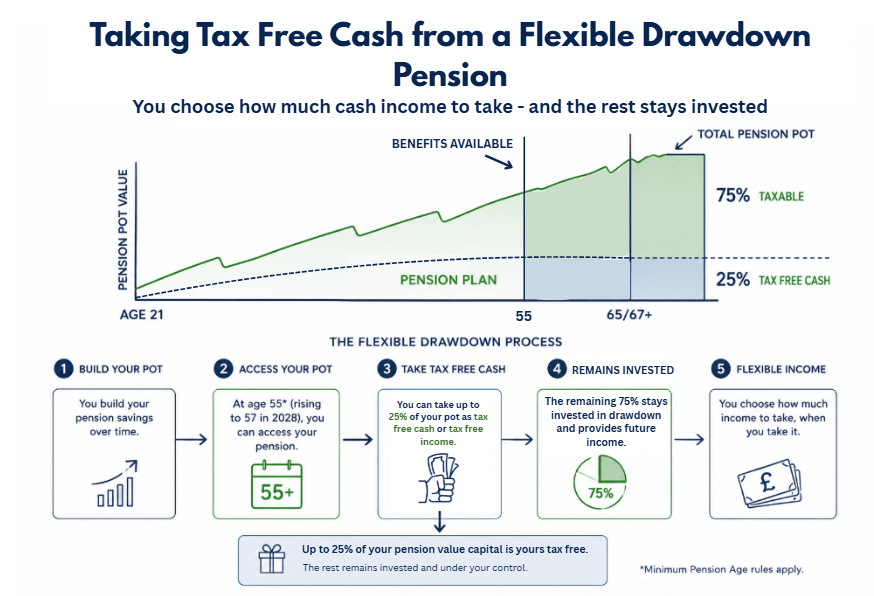
The following diagram shows a view of how a pension fund is built up throughout a working life. |
|
|
|
1. Let us assume the starting point is from age 21. Contributions (minimum) from the employer 3% and employee 5% of gross income are paid into the pension and invested to grow towards retirement ages.
2. You can access your pension from age 55 (57 in 2028) either as lump sums or income. 3. Up to 25% of your total pension value can be taken tax free, either as lump sums or income.
4. After taking all the tax-free allowance, the remainder stays invested but any further withdrawals are taxed at source by the pension company at 20%. 5. The balance can be taken as you wish, but usually as taxed monthly income. |
|
|
The current Government rule on pensions is that you can only have 25% of the pension value as tax-free cash. This is simple to achieve with the “old style” pensions where you only had the options of taking a full pension income through the purchase of an annuity or taking the 25% tax free cash as a lump sum and a reduced annuity. This is still the case with the so called “Gold plated Government Final Salary Pensions”.
Whereas, with the modern Flexible Drawdown Pension, the tax free element can be taken as partial lump sums or as monthly income.
So how is this achieved?
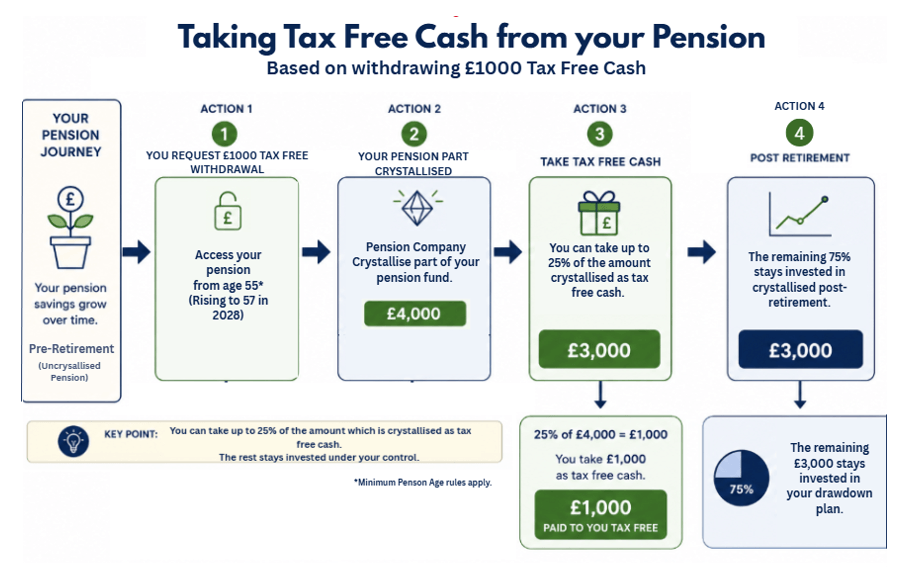
The following diagram sets out to explain the process that the pension companies have designed to meet the rule of only 25% of withdrawals is allowable tax free. |
|
|
|
The diagram assumes from the age of 55, withdrawing £1,000 from the pension value. The pension company crystalises £4,000 from Pre-Retirement account to a Post-Retirement Account. Then withdraws £1,000 from the £4,000 (being 25%) to pay £1,000 tax free. The balance of £3000 remains invested in the Post-Retirement Account and can be accessed taxed at 20%.
As more tax-free cash/income is taken from the pension, the Pre-Retirement Account will gradually get smaller and the Post-Retirement Account will gradually get bigger and continue to be invested to grow for the future. |
|
|
Hope this helps, but please contact us if you wish to have any further explanation.
I hope we can all enjoy the changing colours of Autumn.
Best regards, Ray
|
|
|
|